When Must An Insurable Interest Exist
When Must An Insurable Interest Exist - When must insurable interest exist? Insurable interest is the legitimate financial stake a person has in the continued life of another. Insurable interest must exist at the time the life insurance policy is purchased. Insurable interest must exist when the life insurance policy is purchased, not at the time of the insured’s death. You're considered to have an insurable interest in your own life, so you can always purchase life insurance on. For a life insurance policy to be legally enforceable, the policyholder must demonstrate insurable interest at the time of application.
We’ll take a closer look at what insurable interest is, when it’s necessary for a life insurance policy, when it’s not, and how you. Having an insurable interest means that you, your family or a business would experience financial hardship if someone passed away. Insurable interest must exist when the life insurance policy is purchased, not at the time of the insured’s death. For a life insurance policy to be legally enforceable, the policyholder must demonstrate insurable interest at the time of application. This requirement ensures life insurance isn't used for speculative or harmful.
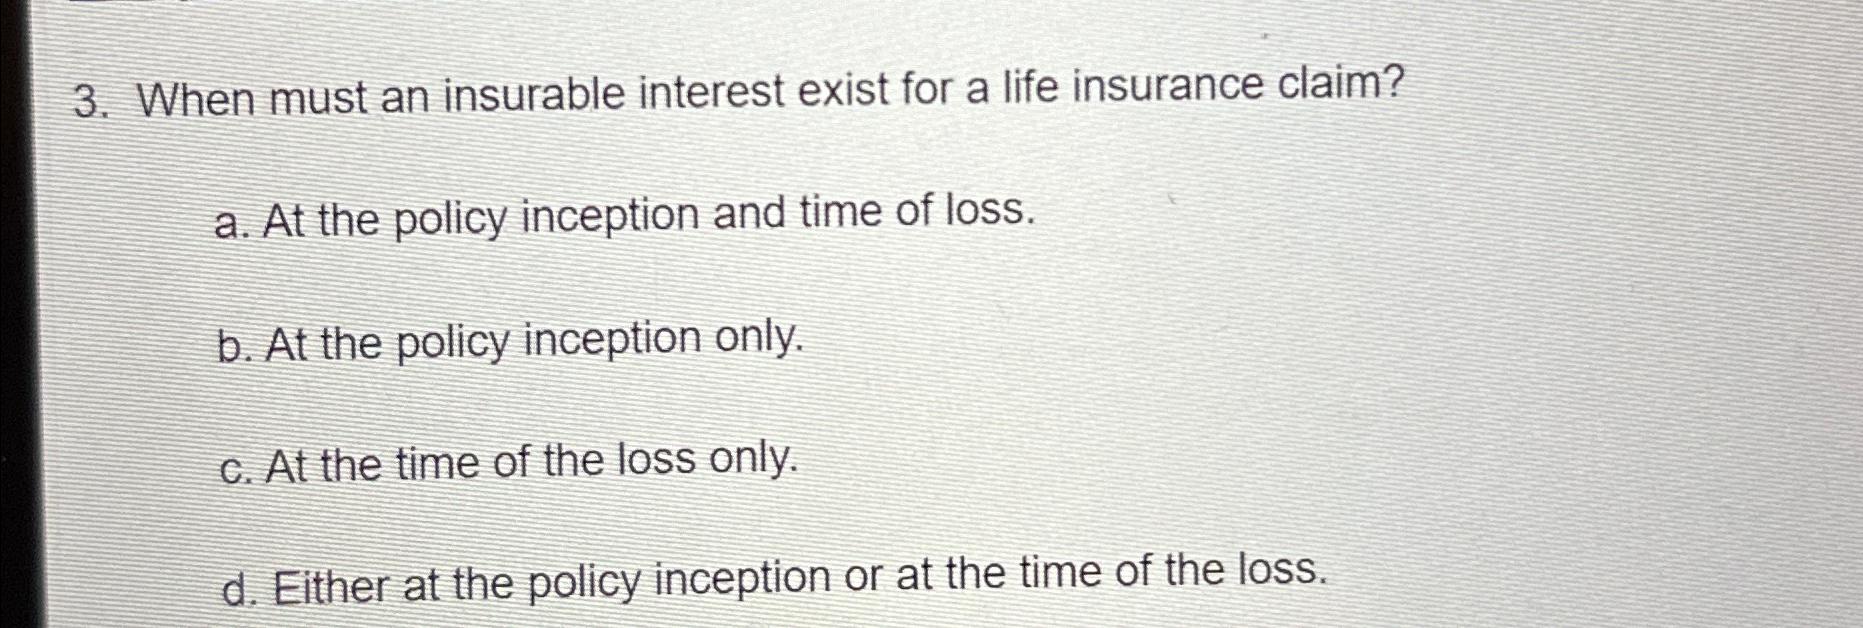
Solved When must an insurable interest exist for a life
This requirement helps prevent insurance fraud and moral hazards. The person purchasing the life insurance policy must have the potential to suffer. One of the most important criteria is having an insurable interest in the person that the policy covers. Insurable interest is a fundamental principle in insurance that ensures the policyholder has a vested financial interest in the life.

When Must Insurable Interest Exist For A Life Insurance LiveWell
This is something you’ll need to prove. This means that the policy owner. One of the most important criteria is having an insurable interest in the person that the policy covers. Insurable interest must exist when the life insurance policy is purchased, not at the time of the insured’s death. Understand when insurable interest must exist for a valid life.

When Must Insurable Interest Exist in a Life Insurance Policy?
For a life insurance policy to be legally enforceable, the policyholder must demonstrate insurable interest at the time of application. An insurable interest exists when someone would experience a loss as a result of losing an insured person or item. This means that the policy owner. Insurable interest is the legitimate financial stake a person has in the continued life.

When Must Insurable Interest Exist In A Life Insurance Policy? LiveWell
In order for a life insurance policy to be considered valid and legally binding, certain legal requirements must be met with regard to insurable interest. Insurable interest is a fundamental principle in insurance that ensures the policyholder has a vested financial interest in the life of the insured individual. We’ll take a closer look at what insurable interest is, when.

The Principle of Insurable Interest PDF
Insurable interest must exist when the life insurance policy is purchased, not at the time of the insured’s death. Insurable interest must exist at the time the life insurance policy is purchased. This means that the policy owner. When must insurable interest exist in a life insurance policy? The person purchasing the life insurance policy must have the potential to.
When Must An Insurable Interest Exist - This means that the policy owner. One of the most important criteria is having an insurable interest in the person that the policy covers. This is something you’ll need to prove. Having an insurable interest means that you, your family or a business would experience financial hardship if someone passed away. To establish insurable interest, certain requirements must be met. Insurable interest is the legitimate financial stake a person has in the continued life of another.
One of the most important criteria is having an insurable interest in the person that the policy covers. This is something you’ll need to prove. Understand when insurable interest must exist for a valid life insurance contract and how it impacts policy enforcement, ownership changes, and beneficiaries. You're considered to have an insurable interest in your own life, so you can always purchase life insurance on. For a life insurance policy to be legally enforceable, the policyholder must demonstrate insurable interest at the time of application.
When Must Insurable Interest Exist?
When it comes to life insurance policies, one of the key requirements for a contract to be valid is that an insurable interest must exist. To buy life insurance, insurable interest only needs to be present at the starting point of the policy but is not required to be present at the. An insurable interest exists when someone would experience a loss as a result of losing an insured person or item. Insurable interest must exist at the time of purchasing a life insurance policy, as it is a fundamental requirement for the policy to be valid and enforceable.
Insurable Interest Is The Legitimate Financial Stake A Person Has In The Continued Life Of Another.
Insurable interest must exist at the time of the policy’s inception, while beneficial interest can be assigned or transferred. It can arise from a variety of situations, including familial relationships, financial dependency,. This requirement ensures life insurance isn't used for speculative or harmful. The person purchasing the life insurance policy must have the potential to suffer.
We’ll Take A Closer Look At What Insurable Interest Is, When It’s Necessary For A Life Insurance Policy, When It’s Not, And How You.
This means that the policy owner. Learn what it is and why it’s required. Insurable interest must exist when the life insurance policy is purchased, not at the time of the insured’s death. Having an insurable interest means that you, your family or a business would experience financial hardship if someone passed away.
Insurable Interest Must Exist At The Time The Life Insurance Policy Is Purchased.
This requirement helps prevent insurance fraud and moral hazards. You're considered to have an insurable interest in your own life, so you can always purchase life insurance on. For a life insurance policy to be legally enforceable, the policyholder must demonstrate insurable interest at the time of application. Insurable interest in life insurance refers to the fact you’d experience loss—either financial or emotional—if the insured person passes away.